
El mercado de marihuana medicinal en Florida tiene un guardián de $5 millones. Qué exige la ley de la fianza MMTC, cuándo vence, cuánto cuesta y cómo reducirla a $2 millones.
Florida’s medical marijuana market has a $5 million gatekeeper. What the MMTC bond law requires, when it’s due, what it costs, and how established operators cut it to $2 million.
Florida otorgó 22 nuevas licencias MMTC el 11 de septiembre de 2026. Esto es lo que sigue: la fianza de $5M, compensación laboral, seguros del local y el paquete operativo.
Florida granted 22 new MMTC licenses on September 11, 2026. Here is what new licensees need next: the $5M bond, workers’ comp, lease insurance and the operating stack.
Todas las pólizas que necesita un dispensario con licencia en Florida en 2026, desde la fianza MMTC de $5M y la compensación laboral hasta lo que exigen arrendadores y socios.
Every policy a licensed Florida dispensary needs in 2026, from the $5M MMTC bond and workers’ comp to the coverages your landlord and partners will require.
Lo que pagan los negocios de cannabis en Florida por su seguro en 2026: rangos por tipo de negocio, qué mueve la prima y el costo de la fianza MMTC de $5M
What Florida cannabis businesses pay for insurance in 2026: reference ranges by business type, what moves the premium, and the $5M MMTC bond cost.
Delta-8 loses federal hemp status on November 12, 2026, and THCA flower and hemp delta-9 follow on December 11. If your Florida smoke shop, CBD store or hemp brand sells these products, your products liability coverage may disappear with them. Here's what changes, how it hits your policy, and the steps to take before the deadlines.
Get Insured Online in 5 Minutes in NYC: 6 Carriers You can Apply to Yourself
No calls, no emails, no waiting. Six carriers on our Get a Quote page let New Yorkers apply online and get covered in about 5 minutes — business liability, workers' comp, commercial auto, renters and pet insurance. Here's which one fits you
Seguro de Drayage en Miami: el Trailer Interchange, Explicado
La cobertura que decide si PortMiami te deja jalar una caja no es el liability ni los daños físicos — es el trailer interchange. Aquí te explico qué cubre, por qué la terminal lo exige, y cuánto cuesta un programa completo de drayage en Miami en 2026.
Port Dayage Insurance in Miami: Trailer Interchange, Explained
The coverage that decides whether PortMiami lets you pull a box isn't liability or physical damage — it's trailer interchange. Here's what it covers, why the terminal requires it, and what a full Miami drayage program runs in 2026.
Farm-to-Market Trucking Insurance Hudson Valley & Finder Lakes
Produce, dairy, grapes, equipment — hauling agriculture in upstate NY has its own rules. Here's what the covered farm vehicle (CFV) exemption does and doesn't do for you, the coverages that fit farm-to-market (including spoilage cargo), and the moment hauling for hire flips you into full for-hire motor carrier territory.
Upstate vs. NYC Tricking Insurance: Why Your Rate Depends on Where You are Garaged
"Why is my quote so much higher than a guy running the same truck upstate?" It usually isn't the truck or the driver — it's geography, baked into how commercial auto is rated. Here's how garaging ZIP sets your territory factor, why NYC prices at the top, why upstate is cheaper but still not cheap, and the risk factors you can actually control.
Cross-Border Trucking Insurance: Buffalo/Niagara to Canada
Western New York is one of the busiest freight gateways to Canada — but crossing the border changes your risk and compliance, and a US-only setup can leave you exposed the moment you clear customs. Here's the cross-border checklist: extending your coverage territory into Canada, meeting the $1M Canadian minimum, getting a CBSA carrier code, adding Canadian jurisdictions to IRP/IFTA, and staying clear of cabotage.
Cargo Theft in New York & New Jersey:What Your Cargo Insurance Actually Covers
Cargo theft losses rose about 60% in 2025 to roughly $725M, and New Jersey thefts jumped 50%. Here's what motor truck cargo insurance covers, the exclusions that deny theft claims (unattended vehicles, high-theft goods, fake pickups), and how NY truckers and brokers close those gaps.
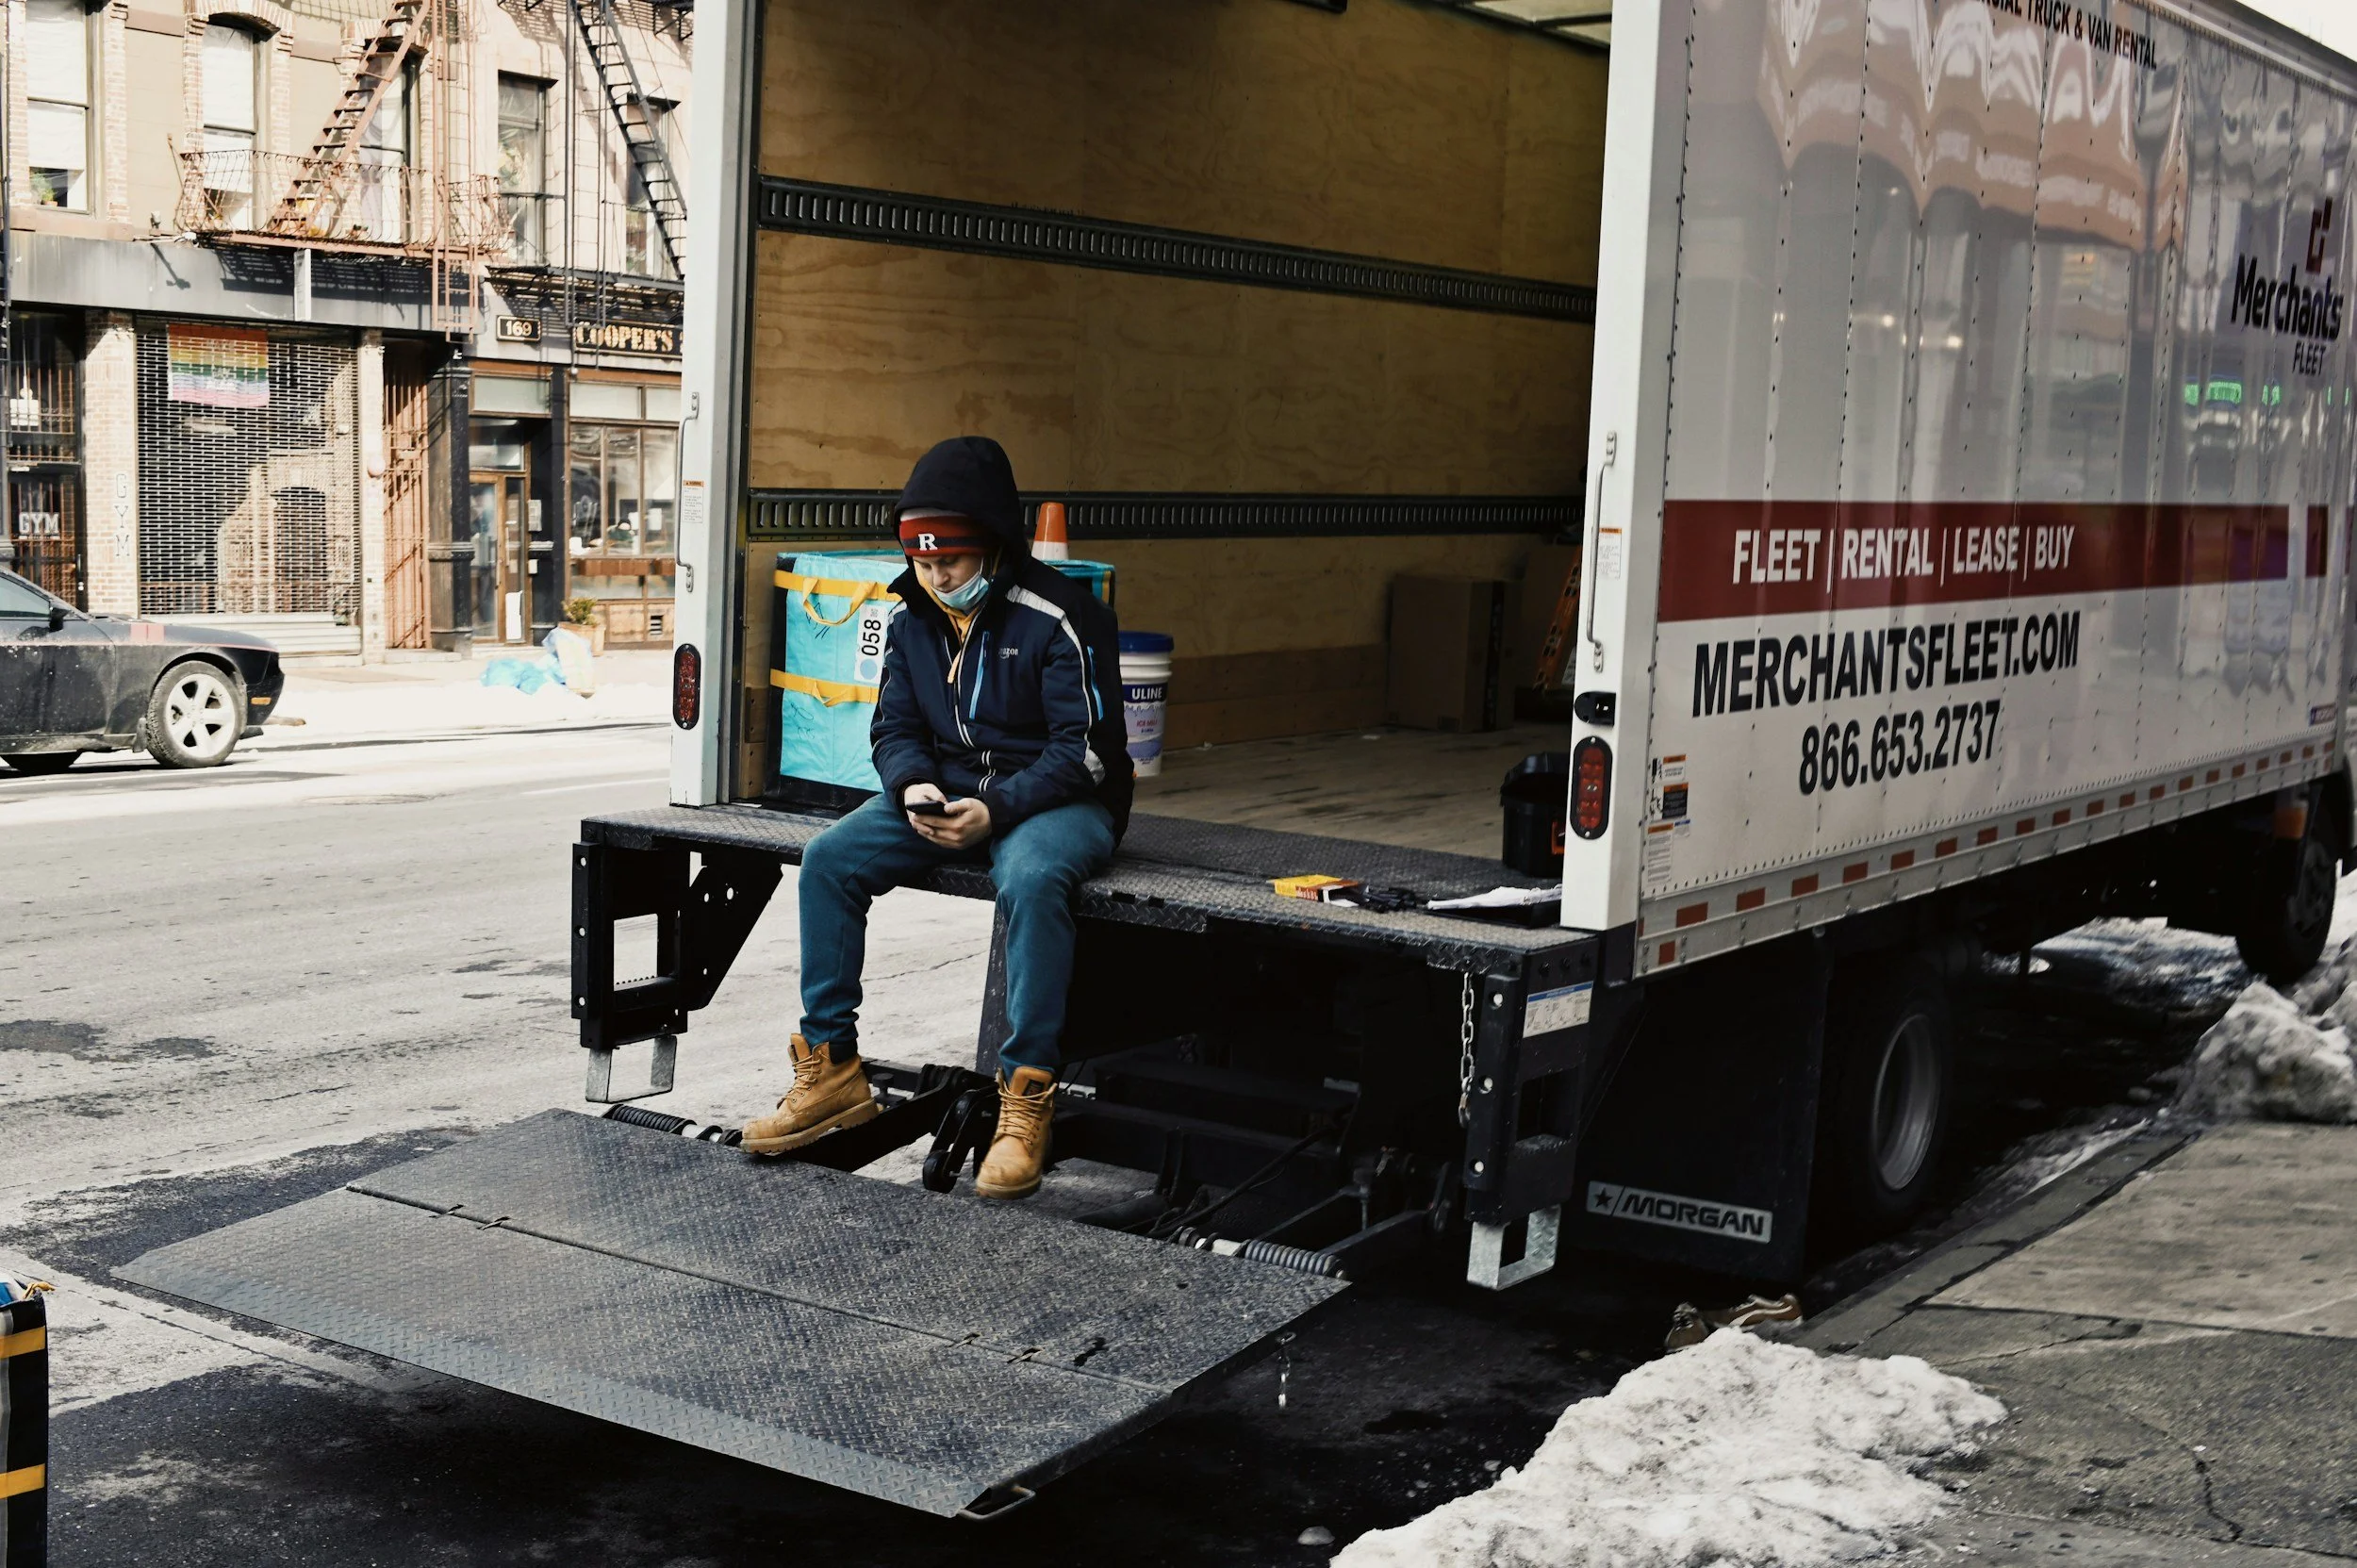
Moving Company Insurance in New York: NYSDOT Household Goods Requirements
New York movers need NYSDOT household goods authority, Form E and Form H filings, cargo coverage of at least $5K per vehicle / $10K per occurrence, and workers' comp from the first hire. This guide covers what intrastate and interstate movers must carry, plus what NYC buildings expect on your COI.
Tow Truck Insurance NYC: DCWP License Requirements & 2026 Costs
NYC tow companies can't get a DCWP license without proof of insurance: $200K/$500K bodily injury, $50K property damage and $25K on-hook, or a $1M combined single limit plus $25K on-hook. Here are the full requirements, bond and fees, and what a tow program really costs in 2026.
Fianzas vs. Seguro para Contratistas PEMEX: Qué Exige Cada Uno (y Dónde se Traslapan
Son dos instrumentos distintos que muchos contratistas confunden — y esa confusión puede dejarlo sin contrato, o peor, sin protección real cuando algo sale mal en campo.
7 Errores Comunes al Asegurar tu Camión en Florida
Estos son los errores que vemos una y otra vez entre dueños-operadores en Florida — y que no se descubren hasta que ya es demasiado tarde: en el momento de un accidente.